Choosing a fixed rate or variable mortgage depends on your budget, plans and risk tolerance. Learn what suits you before you commit.
A difference of a few percentage points can change your monthly mortgage payment by hundreds of pounds. That is why the question of a fixed rate or variable mortgage is rarely just about interest rates. It is about how much certainty you want, how long you expect to stay put, and how comfortably your finances could cope if rates move.
For some borrowers, the right answer is obvious. For others, it only becomes clear once you look at your wider plans, not just the initial headline rate. A mortgage should fit your circumstances now and still make sense if life changes over the next few years.
Fixed rate or variable mortgage: what is the difference?
A fixed rate mortgage gives you an interest rate that stays the same for a set period, often two, three, five or ten years. During that fixed term, your monthly mortgage payment for the loan itself will not change, which can make budgeting much easier.
A variable mortgage, by contrast, can go up or down. That might mean a tracker mortgage which follows the Bank of England base rate by a set margin, or a standard variable rate set by the lender. If rates fall, your payment may reduce. If rates rise, your payment may increase.
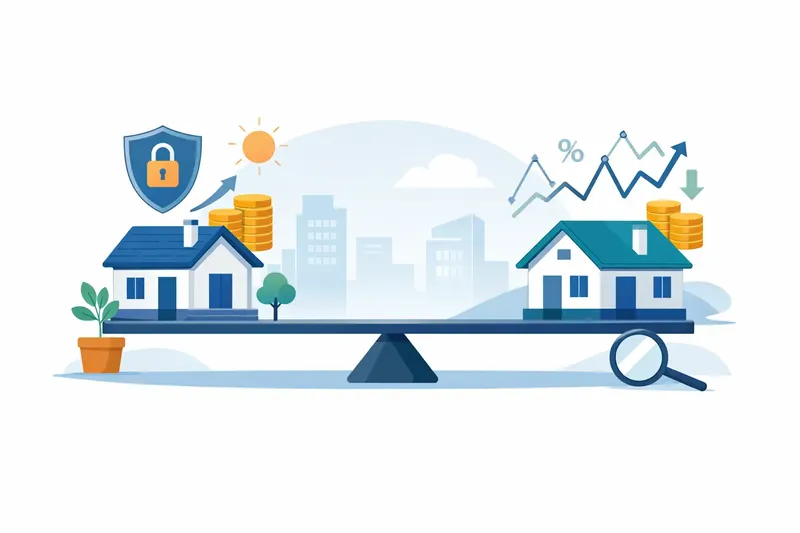
That sounds simple enough, but the real decision sits in the trade-off. Fixed rates offer certainty. Variable rates offer flexibility and, in some market conditions, a lower starting cost. Neither is automatically better. Suitability depends on your circumstances.
When a fixed rate mortgage often makes sense
If you like knowing exactly what will leave your account each month, a fixed rate can be very reassuring. This is especially true for first-time buyers, families with tight monthly budgets, or anyone stretching affordability to buy the home they really want.
A fixed rate can also suit borrowers who expect household costs to stay high for a while. If childcare, school fees, commuting costs or other financial commitments already make budgeting feel tight, the last thing you may want is uncertainty over your mortgage payment.
There is also a practical point here. Peace of mind has value. Some clients are happy to pay a little more for the comfort of knowing their mortgage payment will stay steady for several years. That does not make them overly cautious. It simply means they value stability.
The downside is that fixed products often come with early repayment charges during the fixed term. If you redeem the mortgage, overpay beyond the product allowance, or switch away too soon, there can be a cost. So while the monthly payment may be predictable, your flexibility can be more limited.
When a variable mortgage may be the better fit
A variable mortgage may appeal if you can cope with some movement in monthly payments and want the chance to benefit if rates reduce. Tracker mortgages are often popular with borrowers who are comfortable watching the market and who understand that lower payments are not guaranteed.
Variable products can also be useful if you do not expect to keep the mortgage for long. For example, if you are likely to move home, sell a property, or refinance in the near future, a variable deal with lower fees or fewer tie-ins may be attractive.
Some borrowers simply have more room in their finances. If an increase in rates would be manageable rather than stressful, a variable option may feel less risky. In that case, the question becomes less about protection and more about strategy.
Still, variable means exactly that. If rates rise sharply, so can your payment. A mortgage that feels affordable today needs to remain affordable if the market changes.
Fixed rate or variable mortgage for first-time buyers
First-time buyers often lean towards fixed rates, and there is a good reason for that. Buying your first home comes with enough unknowns already. Solicitors’ costs, moving expenses, furnishing a property, and getting used to all the regular bills can put pressure on your budget.
In that situation, payment certainty is valuable. Knowing your mortgage cost will stay the same for a fixed period can make the whole experience feel more manageable.
That said, not every first-time buyer needs the same approach. Someone buying well within their means may be happy to accept some rate movement, particularly if a variable product gives them a competitive starting point or fewer restrictions. The key is not whether you are a first-time buyer. It is how much financial breathing space you will have after completion.
What homeowners and remortgagers should consider
If you already have a mortgage, your choice may be shaped by timing as much as preference. Are you coming to the end of a deal? Do you want to protect your monthly budget for the next few years? Are you planning renovations, a move, or changes in income?
A remortgage is often a good time to step back and look at the bigger picture. A fixed rate may work well if you want to keep costs steady while other financial commitments grow. A variable option may suit if you expect to review things again soon, or if you think more flexibility matters than rate security.
This is where advice can be particularly helpful. The cheapest-looking product is not always the most suitable once arrangement fees, incentives, tie-ins and future plans are taken into account.
The questions that matter more than the rate itself
When deciding between a fixed and variable mortgage, borrowers often focus on whether rates are likely to rise or fall. That matters, but it is not the whole story. Very few people can predict rate movements consistently, and trying to time the market perfectly is not usually the best way to choose a mortgage.
A better approach is to ask a few practical questions. If your payment rose by a couple of hundred pounds, would that be comfortable or difficult? Are you likely to move within the next two to five years? Do you value certainty more than the possibility of saving money if rates fall? Would early repayment charges be a problem if your plans changed?
These are the questions that turn a broad market decision into a personal one.
Costs, fees and flexibility
Interest rate is important, but it is only one part of the picture. Product fees can change the overall value of a deal, especially on larger or smaller loan amounts. Some fixed rates come with incentives such as free valuation or legal support on remortgages, while some variable products offer lower upfront costs.
You also need to look at overpayment rules and exit charges. If you expect to receive bonuses, inherit money, or want to reduce the balance faster, the flexibility of the mortgage matters. A rate that looks attractive at first can feel far less appealing if it limits your options.
Why the right answer can change over time
The right mortgage choice is not permanent. What suited you two years ago may not suit you now. A borrower with a stable income and no children might once have been comfortable with a variable rate, but after starting a family they may prefer the certainty of a fixed payment. Equally, someone who fixed for security may later want more flexibility when remortgaging.
That is one reason ongoing review matters. Mortgage decisions should reflect where you are now, not just what worked in the past.
For borrowers in Windsor and the surrounding area, as elsewhere, the market can feel crowded and sometimes contradictory. One lender may offer an appealing fixed deal but stricter criteria. Another may have a competitive tracker but less flexibility elsewhere in the product. Looking at rates alone rarely tells the full story.
A broker such as Illingworth Mortgages can help compare both high street and specialist options and weigh them against your plans, not just the headline numbers. That matters whether you are buying your first home, reviewing a residential mortgage, or financing a buy-to-let property.
So, should you choose fixed or variable?
If certainty, stability and easier budgeting matter most, a fixed rate is often the stronger choice. If flexibility, shorter-term thinking, or the potential to benefit from falling rates matter more, a variable mortgage may suit you better.
Neither choice is universally right. The most suitable mortgage is the one that fits your budget, your plans and your comfort with risk. A good decision is not about choosing the cleverest option on paper. It is about choosing the one you will still feel comfortable with after the offer arrives and the keys are in your hand.