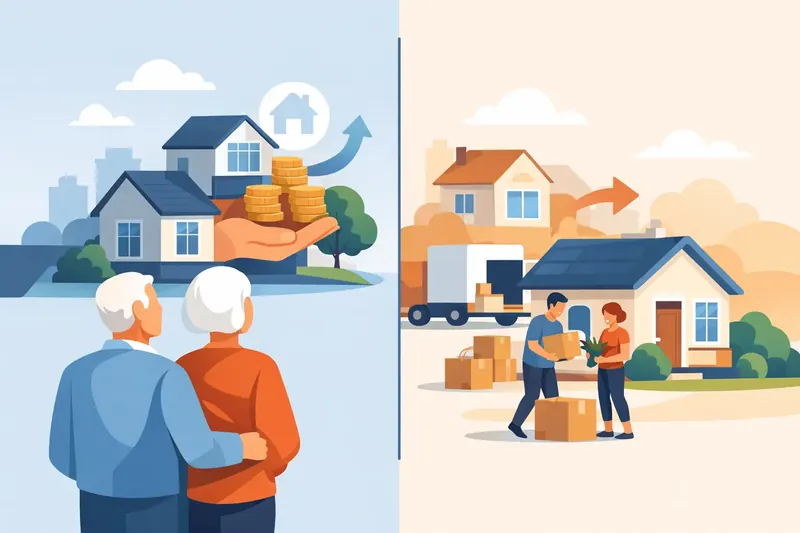
Equity release or downsizing? Compare costs, flexibility and long-term impact to decide which option may suit your retirement plans best.
For many homeowners, the question is not whether there is value tied up in the property, but how best to use it. If you are weighing up equity release or downsizing, the right answer will depend on far more than the headline figure on an estate agent’s valuation. It comes down to income, family plans, health, future care needs and how strongly you feel about staying in your current home.
This is one of those decisions where a simple comparison can be misleading. Both options can free up money, but they do so in very different ways. One allows you to remain in your property while borrowing against it. The other involves selling, moving and usually buying somewhere smaller or less expensive. Neither is automatically better. The most suitable route depends on what you need the money for and what you want life to look like over the next 10 to 20 years.
How equity release or downsizing work
Equity release usually refers to a lifetime mortgage. This lets you borrow against your home while retaining ownership, with the loan typically repaid when the property is sold after death or a move into long-term care. Some plans allow interest to roll up, while others let you make voluntary payments to control the balance.
Downsizing is more straightforward in principle. You sell your current home, buy a cheaper one and keep the difference after costs. In practice, it can still be a major financial and personal step. The amount you release depends not just on the sale price, but on stamp duty, legal fees, removals, possible renovations and the cost of the next property.
That is why the real comparison is not just how much cash you can raise. It is how each option affects your independence, monthly outgoings, estate planning and quality of life.
When equity release may be the better fit
Equity release can make sense for homeowners who are asset-rich but income-light. If most of your wealth is in your property and you want to stay put, it may provide access to funds without the disruption of moving.
This can be particularly relevant if your home already suits later life. You may be near family, close to local services, or in a property adapted for changing mobility needs. In those situations, the emotional and practical cost of moving can be significant. Staying where you are may offer stability that is hard to put a price on.
It can also help where the need for funds is immediate and specific. Some people use equity release to repay an existing mortgage, top up retirement income, support family members with house deposits or cover home improvements. Others want a reserve facility they can draw on only when needed, rather than taking a large lump sum all at once.
That said, equity release is not free money. Interest can build up quickly if it is not being serviced, which reduces the value of the estate over time. There may also be an impact on means-tested benefits, and some plans can affect how much flexibility you have if you want to move later. Good advice matters because product features vary, and suitability depends on the wider picture.
When downsizing may be the stronger option
Downsizing often appeals to homeowners who want a cleaner financial reset. Rather than borrowing against the home, you are releasing capital by changing the property itself. There is no compounding interest to worry about, and whatever cash is left after the move is yours to use as you choose.
For some, the attraction is not just financial. A smaller home may be cheaper to heat, maintain and insure. If your current property feels too large, too expensive to run or no longer practical, moving can improve day-to-day living as well as release equity.
Downsizing may also preserve more of your estate than a lifetime mortgage, depending on property values and the amount of borrowing otherwise needed. If leaving as much as possible to children or other beneficiaries is a priority, that can be an important factor.
But there are trade-offs here too. Moving home can be stressful, and suitable properties are not always easy to find, especially if you want to remain in the same area. In places such as Windsor and nearby towns, smaller properties can still carry a high price tag, which limits how much capital is actually released. Selling costs, purchase costs and the practical upheaval of moving should never be underestimated.
The financial differences that matter most
The biggest financial distinction between equity release or downsizing is what happens over time.
With equity release, you stay in your home but take on borrowing secured against it. If no payments are made, the debt and interest grow, which can significantly reduce equity later. Modern lifetime mortgages often include useful protections, such as a no negative equity guarantee, but the long-term cost still needs careful attention.
With downsizing, the cost is more visible and immediate. You will know your sale proceeds, purchase price and moving costs fairly early in the process. There is no loan balance growing in the background. However, if you move to an area you do not like, or to a property that proves unsuitable, changing course again may be expensive and impractical.
Tax is another area people often ask about. In many cases, the cash released from selling your main residence is not subject to Capital Gains Tax, though personal circumstances vary. Equity release proceeds are borrowed funds, not income, but they can still affect means-tested benefits and broader financial planning. This is why mortgage advice often needs to sit alongside legal and, where appropriate, financial planning support.
The personal questions people often miss
Some decisions look straightforward on paper and feel very different in real life. This is one of them.
If you are considering equity release, ask yourself how important it is to remain in your current home. Is it the property itself you love, or simply the familiarity of the area? If the house has stairs, large gardens or ongoing maintenance demands, will it still suit you in five or ten years?
If you are leaning towards downsizing, think beyond the sale. Will the new property support your needs as you get older? Will you still have space for visiting family, hobbies or overnight carers if ever needed? A move that saves money now can still feel like the wrong choice if it reduces comfort or independence later.
Family conversations also matter. Some homeowners avoid discussing these choices because they do not want advice to feel like pressure. In reality, a calm discussion can help uncover practical issues early, especially where inheritance expectations, informal care or future living arrangements may come into play.
Equity release or downsizing in later-life planning
The best decision is often the one that supports the life you want, not just the balance sheet you prefer.
If your priority is staying in a familiar home and you have enough equity to make the borrowing sustainable, equity release may be worth serious consideration. If your home no longer suits your lifestyle and you would welcome lower running costs and a fresh start, downsizing may be the more sensible route.
There is also a middle ground. Some homeowners explore downsizing first, then consider whether a smaller amount of later-life borrowing might help in the future if needs change. Others rule out one option quickly once they see the numbers properly laid out. The key is not to force a choice too early.
This is where tailored advice can be especially valuable. A proper review should look at the property, your income, health, family priorities, inheritance goals and whether there are alternative ways to meet the need for funds. Illingworth Mortgages supports clients through that process in a way that keeps the decision practical and personal, rather than reducing it to a single product conversation.
A home is more than an asset, but it is an asset as well. When you are deciding between equity release or downsizing, the most helpful next step is usually not to rush towards either option, but to understand clearly what each one would mean for your finances, your family and your future peace of mind.